


 Inversiones Maslosa / Insights / Blog / don’t focus solely on returns: how to analyse an investment fund
Blog
Diversification, Profitability and Added Value
Inversiones Maslosa / Insights / Blog / don’t focus solely on returns: how to analyse an investment fundBLOG
Opinion and economic analysis
DON’T FOCUS SOLELY ON RETURNS: HOW TO ANALYSE AN INVESTMENT FUND.
A common question when discussing investing is: Where can I invest my money without taking on excessive risk?
Everyone has a different financial situation, objectives and risk tolerance, which means that there are no universal solutions that are suitable for everyone. However, the question makes perfect sense.
When we invest our savings, we are concerned not only with how much we can earn, but also with how much we are willing to risk to achieve that return. Finding this balance is essential to making investment decisions that are consistent with our needs and expectations.
However, when it comes to investing, I believe there is one thing we need to be clear about: the fund that delivers the highest return is not always the best one, nor is the fund with the smallest fluctuations necessarily the most suitable for us.
Imagine comparing two investment funds, one of which has performed better than the other. At first glance, the choice might seem obvious. But what if that higher return was achieved by taking on considerably more risk? What if the other fund had delivered similar results with a more favourable risk-return relationship? Or what if the first fund charged considerably higher fees without delivering results that justified the additional cost?
The answer changes considerably.
And this brings us to one of the most important considerations when investing: we should not evaluate a fund solely on how much money it makes, but also on how it generates those returns and what level of risk it takes to achieve them.
The key lies in understanding what lies behind the results.
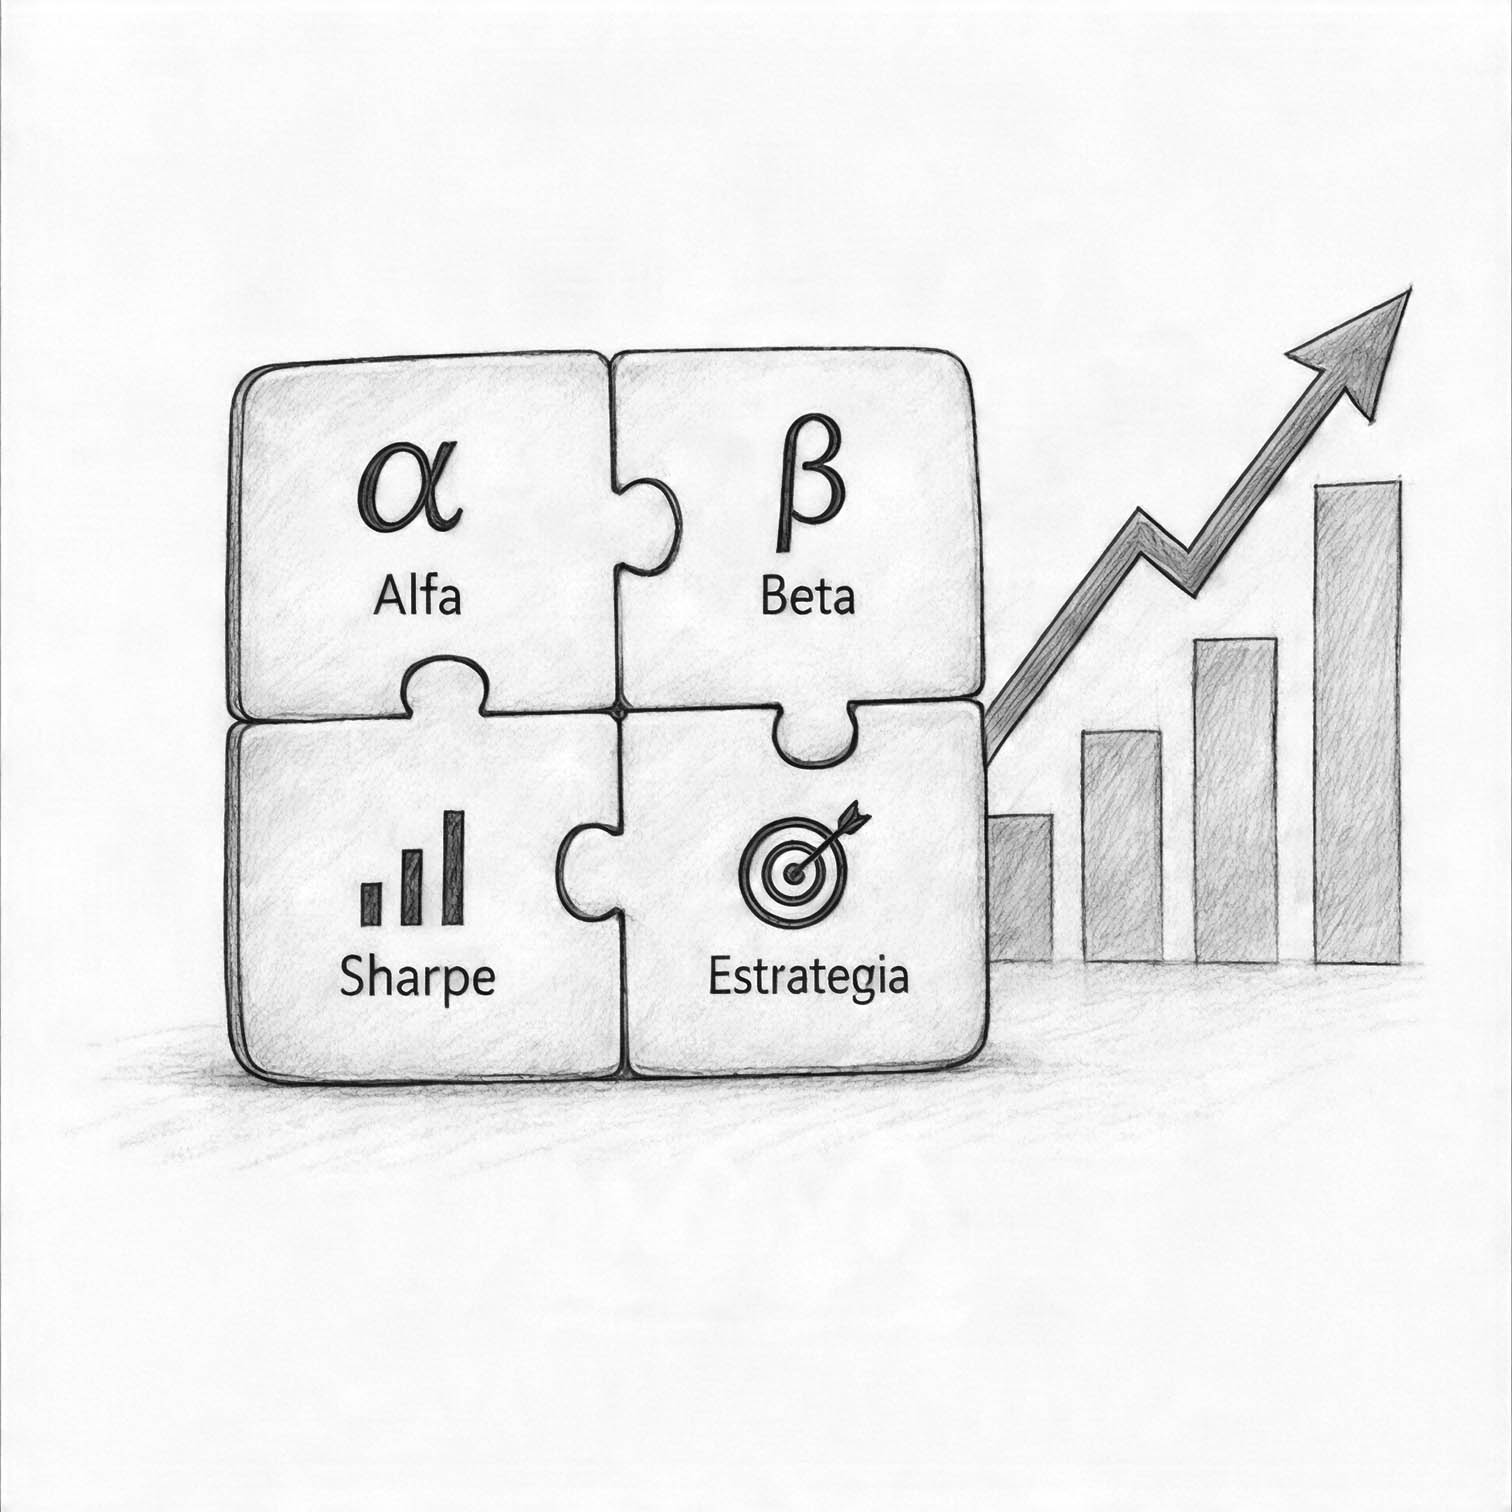
To do so, three indicators are particularly useful: alpha, beta and the Sharpe ratio. Understanding them allows us to move beyond a superficial assessment of funds towards a much more professional analysis.
1. Alpha: measuring an investment’s excess return.
When analysing an investment fund, it is not enough to look at how much it has earned. It is also important to determine whether that return is consistent with the risk taken and whether it genuinely delivers an additional benefit compared with an appropriate benchmark. This is where alpha comes into play.
Alpha is a measure that seeks to quantify a fund’s return above or below the return expected under a given risk model. In other words, it helps assess whether performance has exceeded what could be explained by market exposures and the risk factors considered in that model alone.
Imagine an investment strategy focused on large US companies. During a given period, the market experiences a particularly favourable phase, and most of these companies appreciate significantly in value.
The fund performs well, but the relevant question is whether it has managed to outperform what could reasonably have been achieved through comparable exposure to the market.
If the fund delivers a return similar to that of its benchmark index despite incurring higher costs, it is reasonable to question whether those additional costs are genuinely justified.
Conversely, positive alpha may indicate that the fund has generated a return above that expected under the model used. However, it is worth assessing whether this result is consistent, statistically significant and sustainable, as well as checking the impact of fees and the suitability of the benchmark index.
My view: alpha is particularly useful for assessing whether an investment is delivering additional value or whether its performance can be explained primarily by market movements.
However, we should not interpret positive alpha as a guarantee of good future performance. Historical returns may be partly influenced by market factors, exceptional circumstances or exposures that will not necessarily be repeated.
Therefore, rather than focusing on a single figure, we should analyse the consistency of performance, the costs and the risk taken.
The key question is: Is my investment generating additional value that justifies its costs, or could I achieve a similar result through a more cost-efficient alternative?
2. Beta: what happens to our investment when the market falls?
Beta measures an investment’s sensitivity to movements in a benchmark index.
This indicator helps us understand whether a fund tends to amplify market movements or has historically shown lower sensitivity.
Consider a portfolio of technology stocks. Given its composition, it may be particularly sensitive to changes in interest rates, growth expectations and company valuations.
Another equity portfolio, more diversified across sectors and with different characteristics, might show lower sensitivity to the same index.
Beta helps us examine some of these differences, although its interpretation depends on the index selected and the period analysed.
A beta above one generally indicates greater historical sensitivity than that of the benchmark market. A beta below one indicates lower sensitivity. A beta close to one suggests similar sensitivity.
However, an important distinction needs to be made: beta does not predict exactly how much a fund will fall or rise in the next market session. It describes a historical statistical relationship.
Nor does it measure every type of risk. A fund may have a low beta and still carry significant risks arising from concentration, liquidity, credit exposure or the use of certain financial instruments.
My view: we should not pursue the lowest possible beta or assume that a high beta necessarily makes an investment a bad choice. What matters is determining whether the market exposure is consistent with the portfolio’s objective, the investment horizon and our financial and emotional capacity to withstand losses.
A strategy may be perfectly designed to accommodate volatility. The problem arises when we take on risks we do not understand or do not need to take to achieve our objectives.
3. Sharpe ratio: how much return do we earn for the risk we take?
Returns should be analysed in relation to the risk taken to achieve them.
The Sharpe ratio compares an investment’s excess return over a risk-free rate with the volatility of its returns over the period analysed.
Its purpose is to answer an essential question: how much additional return have we earned for each unit of volatility experienced?
To understand its usefulness, imagine two investment strategies with similar final results. One has experienced relatively limited fluctuations, while the other has undergone much sharper movements.
If both have achieved comparable returns, the first may have a higher Sharpe ratio and therefore a more favourable historical relationship between excess return and volatility.
This does not mean it is necessarily better in every respect. The Sharpe ratio does not fully capture the risks of extreme losses, and low volatility can conceal risks that do not materialise frequently.
Furthermore, to compare two funds properly, we must use equivalent periods, consistent methodologies and appropriate return benchmarks.
My view: the Sharpe ratio is useful for assessing the historical efficiency of a strategy, but it should never be used in isolation.
A fund does not automatically become more attractive simply because it has a high Sharpe ratio. We need to establish how that result was achieved, which risks fall outside the measure and whether the strategy remains suitable for us.
Returns matter, but how they are achieved matters too.
Beyond returns: what determines an investment’s performance?
So far, we have examined three indicators that help assess different aspects of an investment. However, another important question arises when trying to understand how our wealth evolves over the long term:
What factors actually determine the performance of our investments?
This question is particularly relevant because our final wealth does not depend solely on the funds we select. It also depends on how the portfolio is structured, how risks are allocated and how we react to market events.
We may have access to excellent products and still achieve disappointing results if we constantly change our strategy, concentrate too much of our wealth in a few investments or abandon our investments at the worst possible times.
Similarly, a well-designed plan can help us maintain a long-term perspective, control costs and avoid impulsive decisions.
Therefore, to analyse an investment comprehensively, it is worth paying attention to several factors:
1st.In wealth planning, before selecting products, it is necessary to understand liquidity needs, the investment horizon, financial objectives and potential future liabilities.
2nd.In asset allocation, distributing wealth across different asset classes is often a fundamental strategic decision. Selecting good funds is not enough if their combination creates an unsuitable overall exposure.
3rd.In decision-making, euphoria and fear can lead us to buy after prices have already risen considerably or to sell during a downturn without considering the consequences for our long-term objectives.
4th.In cost and tax management, fees, unnecessary transactions and disinvestment decisions can reduce net returns. Identifying these factors and assessing their implications can make a significant difference over the long term.
5th.In strategy monitoring, a portfolio should be reviewed when objectives, needs or relevant conditions change, but it does not need to be adjusted in response to every market movement.
That said, how can we tell whether an investment strategy is performing as it should?
It is not enough to observe whether our wealth has increased. We should also compare its performance with an appropriate benchmark, taking into account the risk assumed, costs, taxes where applicable and cash flows.
Furthermore, it is important to check whether the decisions made have been consistent with the established objectives and whether the strategy remains suitable for our personal and financial circumstances.
Finally, we should remember that a favourable result does not, by itself, prove that a strategy is sound. The market may temporarily benefit certain investments, just as a reasonable strategy may incur losses in adverse conditions.
The big picture: analyse the strategy, not just the product.
To assess an investment properly, it is worth bringing together four key questions:
• Alpha: has the fund generated a return above that expected under the benchmark model used?
• Beta: how sensitive is the investment to market movements?
• Sharpe ratio: what historical relationship exists between the additional return earned and the volatility assumed?
• Wealth strategy: do the asset allocation and investment decisions contribute to achieving the established objectives?
These questions should be complemented by an analysis of fees, diversification, liquidity, potential extreme losses and the portfolio’s suitability for the investment horizon.
No single indicator can replace this combined analysis. Nor is there a universally superior fund for all investors: a strategy suitable for someone with a twenty-year investment horizon may be inappropriate for someone who needs access to their money over a much shorter period.
The quality of an investment depends both on its characteristics and on the role it plays within the overall portfolio.
Conclusion: the goal is not to earn more at any cost.
In my view, one of the biggest financial mistakes is confusing a strong short-term return with a sound investment strategy.
Results over a given period may be influenced by market movements, high exposure to risk or exceptional circumstances. For this reason, a rigorous investment assessment requires us to look beyond the figures: it is not enough to know how much has been earned; we must also understand how it was achieved and to what extent those results can be sustained over time.
Indicators such as alpha, beta and the Sharpe ratio offer different perspectives for analysing a fund’s returns and risk. However, none of these metrics, on its own, can determine whether an investment is suitable for us. To do that, we must also consider our personal circumstances, investment horizon, liquidity needs and the role each investment plays within our overall wealth.
Chasing the best-performing fund of the past year can lead us to make poor decisions if we overlook the risk taken, the consistency of performance and its suitability for our needs. What truly matters is understanding what we are doing with our money and why.
The goal should not be to maximise returns at any cost, but to build and preserve wealth sustainably, take risks consciously and make decisions that are consistent with our circumstances and priorities.
Ultimately, the question is not how much our money has earned over a specific period, but whether the strategy we follow is bringing us closer to what we genuinely want to achieve.


WHO WE ARE
WHAT WE DO
INVESTMENT AREAS
INSIGHTS

